Investors and the self-employed · Minnesota
DSCR loans and bank statement loans in Minnesota: qualify on the rent or the deposits, not the tax returns.
A DSCR loan qualifies a rental property on its rent, not your income. If the rent covers the full monthly payment, a ratio of 1.0 or higher, the loan works. It needs no tax returns, usually 20 to 25% down, and it can often close in your LLC.
A bank statement loan qualifies a self-employed borrower on 12 or 24 months of deposits instead of tax returns. Both are non-QM loans that most banks don't offer. I place them through dozens of wholesale lenders. One DSCR file in 2026 went from submission to clear-to-close in seven days.
Here's how each one works, what lenders look for, the trade-offs said plainly, and when a conventional loan still wins. I'm licensed in Minnesota, Wisconsin, North Dakota, California and Georgia. Text me your situation and I'll tell you which one fits.
Start here
Which one fits you?
-
Buying or refinancing a rental
DSCR loan
The property qualifies, not you. No W-2s, no tax returns, no personal debt-to-income math. If the rent covers the payment, the loan works, and it can close in your LLC.
How DSCR works -
Self-employed, buying a home to live in
Bank statement loan
Your deposits prove your income instead of a tax return that's been written down to nothing. Twelve or twenty-four months of statements, personal or business.
How bank statement loans work
Self-employed and buying a rental? That's a DSCR loan, because it skips your income entirely. Self-employed with two clean years of tax returns? A conventional loan is usually cheaper, and it's usually where I start.
For investors
What is a DSCR loan, and how does the math work?
DSCR stands for debt service coverage ratio. It's the one number this loan cares about: does the rent cover the payment?
A DSCR loan is a business-purpose loan for rental property. It lives outside the Fannie Mae and Freddie Mac rulebook, so each lender writes its own guidelines. That's why having dozens of them to choose from matters. There's no employment verification and no personal income calculation. The building's own income replaces yours.
DSCR = gross monthly rent ÷ PITIAPITIA is the full monthly payment: principal, interest, property taxes, insurance and any association dues.
Example: a duplex rents for $3,100 a month and the full payment is $2,650. 3,100 ÷ 2,650 = 1.17. The property covers itself with 17% to spare. Below 1.0 the rent doesn't cover the payment and the terms get tougher; 1.0 and up is where the best pricing lives.
How the rent is counted. If the property is leased at or above market, the lease is usually used. If it's vacant, or you're buying it, the appraiser completes a market rent schedule (Fannie Mae's Form 1007) and that number drives the ratio. Short-term rentals work on many programs, using a market analysis or documented history. The rules vary more here than anywhere else, so ask before you count on Airbnb income.
A DSCR cash-out refinance, found through ChatGPT
“I found Nate through ChatGPT while looking for help with a DSCR cash out refinance, and I'm glad I did! He was knowledgeable, responsive, and made the entire process smooth and straightforward. Communication was great from start to finish, and I would highly recommend him to anyone looking for a reliable loan officer!”
KatieDSCR cash-out refinance · Google review, November 2026
DSCR calculator
Does the rent cover the payment?
Two numbers in, the ratio out. The payment is the full PITIA. If you don't have it yet, build it in the mortgage calculator with 20 to 25% down and bring the number here.
The rent covers the payment with 17% to spare. At 1.0 and up is where the best pricing lives.
- $2,650Rent needed for a 1.0 ratio
- $3,312Rent needed for 1.25
- $2,480Biggest payment this rent covers at 1.25
- +$450Monthly cushion, rent minus payment
The example numbers are illustrations, not a quote or an offer. Your ratio depends on the appraiser's rent, the taxes and insurance on the actual property, and the loan you choose. Text me these numbers and I'll run them against real programs.
What lenders want to see
DSCR loan requirements, in plain English
- Ratio of 1.0 or higherfor the best terms. Many programs go down to 0.75 with more down or a higher rate; a few offer no-ratio loans.
- 20 to 25% downon a purchase, and typically about six months of the property's payment in reserves after closing.
- Credit score 620 to 660 minimum700 and up is where the pricing gets good.
- 1 to 4 unit residential propertyincluding condos. Many programs take non-warrantable condos and short-term rentals.
- No income documentsA lease or the appraiser's rent schedule. No tax returns, no W-2s, no debt-to-income ratio.
- Close in your LLCon most programs, with interest-only periods available and no ceiling on how many financed properties you own.
The trade-offs, said plainly. You pay for the underwriting you're skipping, so a DSCR loan costs more than a conventional investor loan. Prepayment penalties are common, usually for the first few years, in structures like 5-4-3-2-1 or a flat percentage. Some programs let you buy them down or out. It's a line-by-line conversation before you sign.
Minnesota property tax. A rental is taxed as non-homestead property. A duplex or triplex you don't live in is taxed at a 1.25% class rate on its full value. A homestead pays 1.00% on the first $500,000. A single-family rental keeps the 1.00% rate but loses the homestead market value exclusion. Either way, the tax line in your payment will be higher than the seller's bill if they lived there. Use the non-homestead number in the PITIA, or the ratio will look better than it is.
Rental licenses. Every rental property in Minneapolis must have a rental license. In Saint Paul, a non-owner-occupied building needs a Fire Certificate of Occupancy, and single-family and duplex rentals have to be registered. Most suburbs have a rental license or inspection of their own. Budget for it. The duplex-and-fourplex market across the Twin Cities is one of the best places in the state to start.
Seven days, submission to clear-to-close
“Nathan's attention to detail and speedy response to items needed made for a smooth transaction that took only 7 days from submission to clear to close!”
Matt S.Account executive at a wholesale lender · Google review, 2026
For the self-employed
What is a bank statement loan, and who is it for?
Your tax returns are built to show the IRS as little income as legally possible. A bank statement loan looks at what actually came in.
A bank statement loan is a mortgage for self-employed borrowers that uses 12 or 24 months of bank statements to prove income instead of tax returns. It's built for business owners, contractors, commission earners and anyone whose write-offs make the tax return look thinner than the business. It's a non-QM loan, outside the Fannie Mae and Freddie Mac rules, and it's one of the loans most banks simply don't offer.
How the income is counted. The lender averages your deposits over the period into a monthly income figure. Personal statements are counted close to face value, with transfers and obvious non-income deposits set aside. Business statements get an expense factor, often around half, or a letter from your CPA stating your business's actual expense ratio. A 1099 loan does the same thing with one or two years of 1099s, and a few programs qualify on a profit-and-loss statement alone.
What you'll need.
- Two years in the business, usually, shown with a license, a CPA letter or a state filing.
- 12 or 24 months of statements from the same accounts, without large deposits you can't explain or a run of overdrafts.
- 10 to 20% down is typical, and a credit score in the 620 to 680 range or better.
- Some reserves, a few months of the new payment in the bank after closing.
Keep business and personal money in separate accounts in the year before you apply, and it gets much easier.
When conventional still wins. If two years of tax returns qualify you, a conventional or FHA loan is cheaper, and that's usually where I start. Fannie Mae's rule is a two-year self-employment history in general, with a one-year path in some cases. I run both ways and show you the difference in writing before you pick.
A business owner's bank statement loan
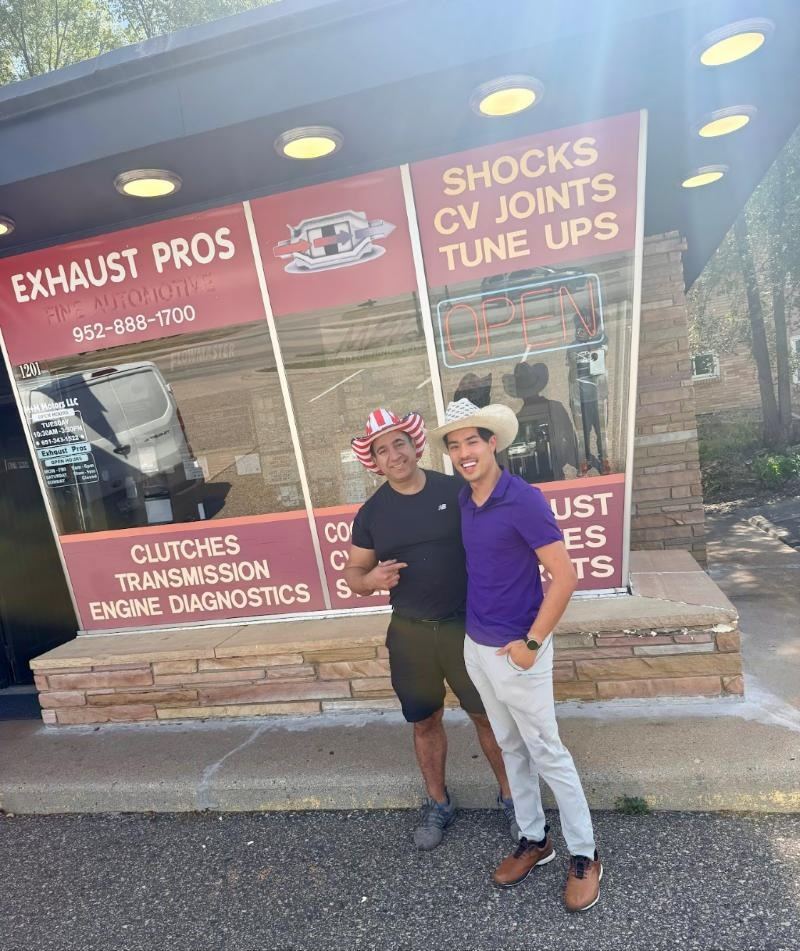
“I own Exhaust Pros, and being self-employed and a business owner made getting a mortgage a little more complicated. Nathan found me a bank statement loan that worked for my situation … It wasn’t an easy loan. There were a lot of steps and things that came up along the way, but Nathan was always responsive, kept me updated, and worked through everything until we got it done. … If you’re self-employed, own a business, or need a bank statement mortgage loan, I definitely recommend Nathan, The Loan Ranger.”
Bos M.Self-employed · Google review, September 2026
Side by side
Conventional vs. DSCR vs. bank statement
Swipe the table sideways
| Conventional | DSCR | Bank statement | |
|---|---|---|---|
| Built for | Documented income, any occupancy | Rental property investors | Self-employed buyers and homeowners |
| How income is proven | Pay stubs, W-2s or two years of tax returns | The property's rent. No personal income at all | 12 or 24 months of deposits, or 1099s |
| Typical minimum down | 3 to 5% to live in; 15 to 25% for a rental | 20 to 25% | 10 to 20% |
| Credit score | Most approvals 620+; best pricing around 740+ | 620 to 660 minimum; 700+ for good pricing | 620 to 680 minimum; better above 700 |
| Property | Primary, second home or investment | 1 to 4 unit rentals, condos, many short-term rentals | Primary, second home or investment |
| Cost, relative | The benchmark | Higher; varies by lender and ratio | Higher; varies widely by lender |
| Prepayment penalty | None | Common for the first few years | Usually none on a home you live in |
| Close in an LLC | No | Yes, on most programs | No |
| Why a broker helps | One application, dozens of lenders priced against each other | Each lender writes its own rules and pricing, so the spread between them is wide. I shop the file across dozens of wholesale lenders and show you the best two or three in writing. | |
Ranges are typical for 2026 programs and change by lender and by file. Everything is confirmed against your numbers. Not a commitment to lend.
Quick answers
DSCR and bank statement loan questions
What DSCR ratio do I need?
A ratio of 1.0 or higher, meaning the rent covers the full payment, gets the best terms on most programs. Many lenders go down to 0.75 with a bigger down payment or a higher rate, and a few offer no-ratio loans. If you're a little short, adding 5% to the down payment is the usual fix, because it lowers the payment and lifts the ratio.
Can I use projected rent or short-term rental income?
If the property is leased at or above market, the lease is usually used. If it's vacant or you're buying it, the appraiser fills out a market rent schedule (Fannie Mae's Form 1007) and that number drives the ratio. Short-term rentals work on many programs, using a market analysis or documented history, but the rules vary more here than anywhere else. Ask me before you count on Airbnb income.
Can I close a DSCR loan in my LLC?
Yes, on most programs. That's one of the main reasons investors choose DSCR over a conventional investor loan, which has to close in your personal name.
Do DSCR loans have prepayment penalties?
Often, for the first few years, in structures like 5-4-3-2-1 or a flat percentage. Some programs let you buy the penalty down or out. I'll show you exactly what yours says before you commit, because it matters if you plan to sell or refinance soon.
How many months of bank statements do I need, 12 or 24?
Programs use either. Twelve months is the lighter lift; twenty-four months often gets better pricing because the lender sees a longer track record. Deposits are averaged into a monthly income figure. With business statements, most programs apply an expense factor, often around half, or use a letter from your CPA stating your actual expense ratio.
Do I need to be self-employed for two years?
Usually. Most bank statement programs want two years in the business, shown with a business license, a CPA letter or a state filing. Some accept one year if you were in the same line of work before. Conventional loans follow Fannie Mae's rule: a two-year history in general, and one year in a few cases.
Do bank statement and DSCR loans cost more than conventional?
Yes. You're paying for the underwriting you're skipping, so the rate and fees run higher than a conventional loan. They vary a lot from one lender to the next. That's exactly where shopping dozens of wholesale lenders earns its keep. If your tax returns qualify you for conventional, that's usually where I start, because it's cheaper.
Can I refinance into a conventional loan later?
Often, yes. Once you have two years of tax returns that qualify you, or once the rental has a season of history, a conventional refinance can lower the cost. Watch the prepayment penalty window on a DSCR loan when you time it.
What credit score do I need?
Most DSCR and bank statement programs start around 620 to 660, and pricing improves a lot at 700 and above. Reserves matter too. For a DSCR loan, plan on about six months of the property's payment in the bank after closing. For a bank statement loan, several months of your own payment.
How fast can a DSCR loan close?
Faster than you'd expect, because there's no income to document. One of mine in 2026 went from submission to clear-to-close in seven days, and the lender's own account executive left a review about it. You get a realistic date on day one; I don't promise a timeline I can't back up.
Let's talk
Text me the address, or just your situation. I'll tell you which loan fits.
No pressure, no pitch. Just a straight answer, evenings and weekends included.
Keep reading
Sources. Self-employment history and documentation for conventional loans: Fannie Mae Selling Guide B3-3.2-01. Market rent schedule: Fannie Mae Form 1007. Minnesota property tax class rates for taxes payable 2026: Minnesota Department of Revenue. Rental licensing: City of Minneapolis and City of Saint Paul. DSCR and bank statement program terms are set by individual wholesale lenders and change; figures here are typical ranges as of October 2026.
Fine print. Not a commitment to lend. All loans are subject to credit approval, underwriting guidelines and property eligibility. The calculator example is an illustration, not a quote. Quotes are exact excerpts from public Google reviews. Nathan Ta, NMLS #2458897, Edge Home Finance, LLC, NMLS #891464, 5860 Baker Road, Minnetonka, MN 55345.